The biggest possible retirement balance is not always the point. What might enough let you do while you still have the time and energy?
The other asset we are spending
We talk about the power of compounding when it comes to money: invest consistently, give it time and let the years do their work. That is sound advice. But while a portfolio grows, we are drawing down another asset at the same time: time itself.
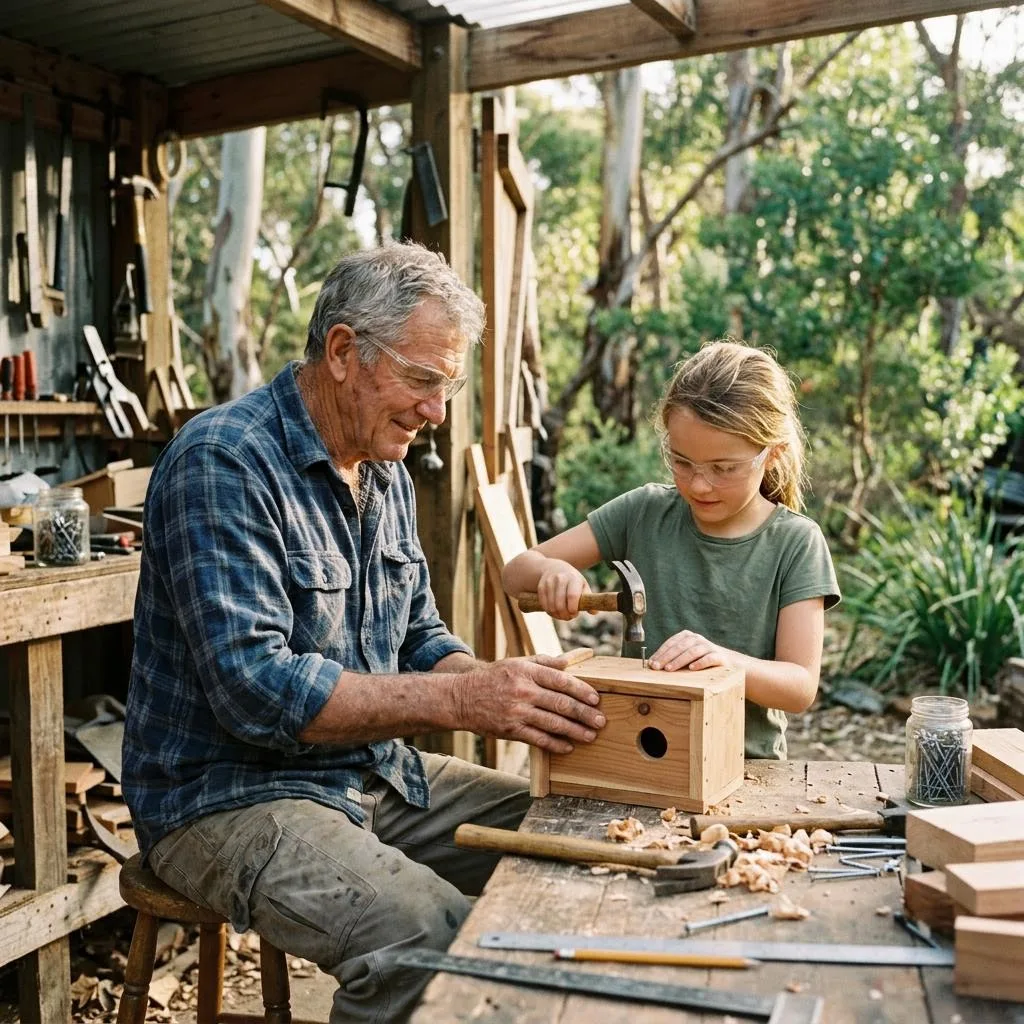
In particular, there are years when we have the health, energy and freedom to do the things we say we are building wealth for. We cannot assume those years will wait for our balance to reach its theoretical maximum.
A harder question than “How much do I need?”
Imagine someone at 50 weighing how much of the next ten healthy years to sacrifice to maximise the number they will have at 60. A financial model can explore retirement balances and spending paths. It cannot decide, on its own, what those ten years are worth to that person.
For one family, enough may mean financial security and the capacity to help their children. For another, it may mean working four days rather than five, travelling sooner, or stepping away from a business they no longer enjoy. The right question is not necessarily “How large can the number become?” but “What choices could this money make possible, and when?”
Planning for both versions of you
This is not an argument for spending everything today. Future You still needs security. But continually deferring life until the next financial milestone also has a cost for Present You.
A useful plan makes that trade-off visible. It tests what you can afford, what could go wrong and how much flexibility you want to retain. Then you can decide, deliberately, whether you have room to start using some of what you have built. You can compound money over time. You cannot compound time later.
This is general information, not advice tailored to you. Your circumstances matter; speak with an authorised adviser before making a financial decision.
WARNING: General advice only. Readers are advised to discuss, with an Authorised Representative, the appropriateness of each recommendation, together with the general and specific risks of investing having regard to personal needs, objectives and financial circumstances. OF Planning Pty Ltd ABN 42670586400 trading as Life First Advice. Dane Pymble (AR323636) is an Authorised Representative of PGW Financial Services Pty Ltd (AFSL 384713 ABN15 123 835 441). All Rights Reserved.
Other perspectives
What do you actually own inside your super?
The name on a super statement is not the same thing as the investments beneath it. Understanding that difference is a better starting point than reacting to headlines.
Read the perspective 02 / Further readingProperty & MarketsAustralian property and the risk beneath the cycle
A comparison with US property history is not a crash forecast. It is a prompt to consider valuation, leverage, employment and liquidity together.
Read the perspective